Quick Summary
Form 10BD is a mandatory statement of donations that certain trusts, institutions and NGOs approved under Section 80G are required to furnish to the Income Tax Department. The statement contains particulars of donations received during the financial year.
The statement is filed electronically through the Income Tax e-Filing portal and must generally be furnished by 31 May immediately following the financial year in which the donations were received. After filing Form 10BD, the organisation must provide donors with the applicable Form 10BE donation certificate.
In this guide, you will learn:
- What is Form 10BD?
- Who needs to file Form 10BD?
- Why is Form 10BD important?
- What information is required?
- Form 10BD due date
- Form 10BD filing process
- What is Form 10BE?
- Difference between Form 10BD and Form 10BE
- Consequences of late or non-filing
- Common mistakes
- Frequently asked questions
Introduction
For NGOs and charitable organisations registered under Section 80G, maintaining accurate donation records is an important part of tax compliance.
One of the key annual compliance requirements is Form 10BD, a statement containing particulars of donations received during the financial year.
Form 10BD enables eligible organisations to report donation information to the Income Tax Department and supports the process through which donors receive Form 10BE, the donation certificate used for claiming the applicable deduction under Section 80G.
The Income Tax Department states that Form 10BD is furnished electronically and requires e-verification through the prescribed methods.
For an NGO, timely and accurate filing is therefore important not only for maintaining compliance but also for ensuring that donor information is correctly reported.
What is Form 10BD?
Form 10BD is a statement of particulars of donations received by specified organisations.
It is required under the Income Tax framework for eligible trusts, institutions and NGOs approved under Section 80G, as well as specified entities covered under Section 35(1A).
The requirement applies to donations received during the relevant financial year.
The organisation reports details relating to its donors and donations through the Income Tax e-Filing portal.
What is the purpose of Form 10BD?
The main purpose of Form 10BD is to enable the organisation to report eligible donation information to the Income Tax Department.
The information reported can then be used for generating the corresponding Form 10BE certificate, which is provided to the donor.
Is Form 10BD mandatory?
For organisations covered by the applicable provisions, Form 10BD is mandatory.
However, the Income Tax Department specifically states that if no donation was received during the financial year, Form 10BD is not required for that year.
Who Needs to File Form 10BD?
Form 10BD is generally applicable to specified trusts, institutions and NGOs that are approved under Section 80G and receive donations for which the donor is eligible to claim deduction under the applicable provisions.
It may also apply to specified entities covered under Section 35(1A).
Organisations that may need to file Form 10BD
These can include:
- Eligible charitable trusts
- Eligible charitable institutions
- NGOs approved under Section 80G
- Other specified institutions covered under the applicable provisions
The exact applicability should be assessed based on the organisation’s registration, approval and nature of donations received.
Why is Form 10BD Important for NGOs?
Form 10BD is an important part of donation reporting and 80G compliance.
1. Helps maintain statutory compliance
Filing the required donation statement within the prescribed timeline helps an eligible organisation meet its reporting obligations.
2. Supports donor tax claims
Accurate reporting of donor information helps facilitate the issuance of Form 10BE, which contains the relevant donation details for the donor.
3. Improves transparency
Maintaining accurate records of donations and reporting them to the Income Tax Department promotes better financial and regulatory transparency.
4. Reduces compliance risks
Incorrect or delayed reporting can result in additional compliance costs and penalties. Therefore, organisations should maintain their donation records throughout the year rather than preparing the information at the last moment.
Information Required for Form 10BD
Before beginning the filing process, the NGO should ensure that the relevant donor and donation records are properly maintained.
Depending on the donation and donor, information may include:
| Information | Purpose |
|---|---|
| Donor Name | Identifies the donor |
| Donor PAN | Tax identification and reporting |
| Donor Address | Donor identification/details |
| Donation Amount | Amount received |
| Date of Donation | Records when donation was received |
| Mode of Donation | Helps classify the contribution |
| Donation Reference | Internal reconciliation |
| Relevant approval details | Organisation’s compliance information |
The exact fields and validation requirements should be checked on the Income Tax e-Filing portal at the time of filing.
Keep donation records organised
It is good practice for an NGO to maintain:
- Donation receipts
- Donor database
- PAN details where applicable
- Bank transaction records
- Cash donation records where applicable
- Online payment records
- Donation reconciliation statements
- Previous Form 10BD filings
- Form 10BE records
This makes the annual filing process considerably easier.
Form 10BD Filing Process
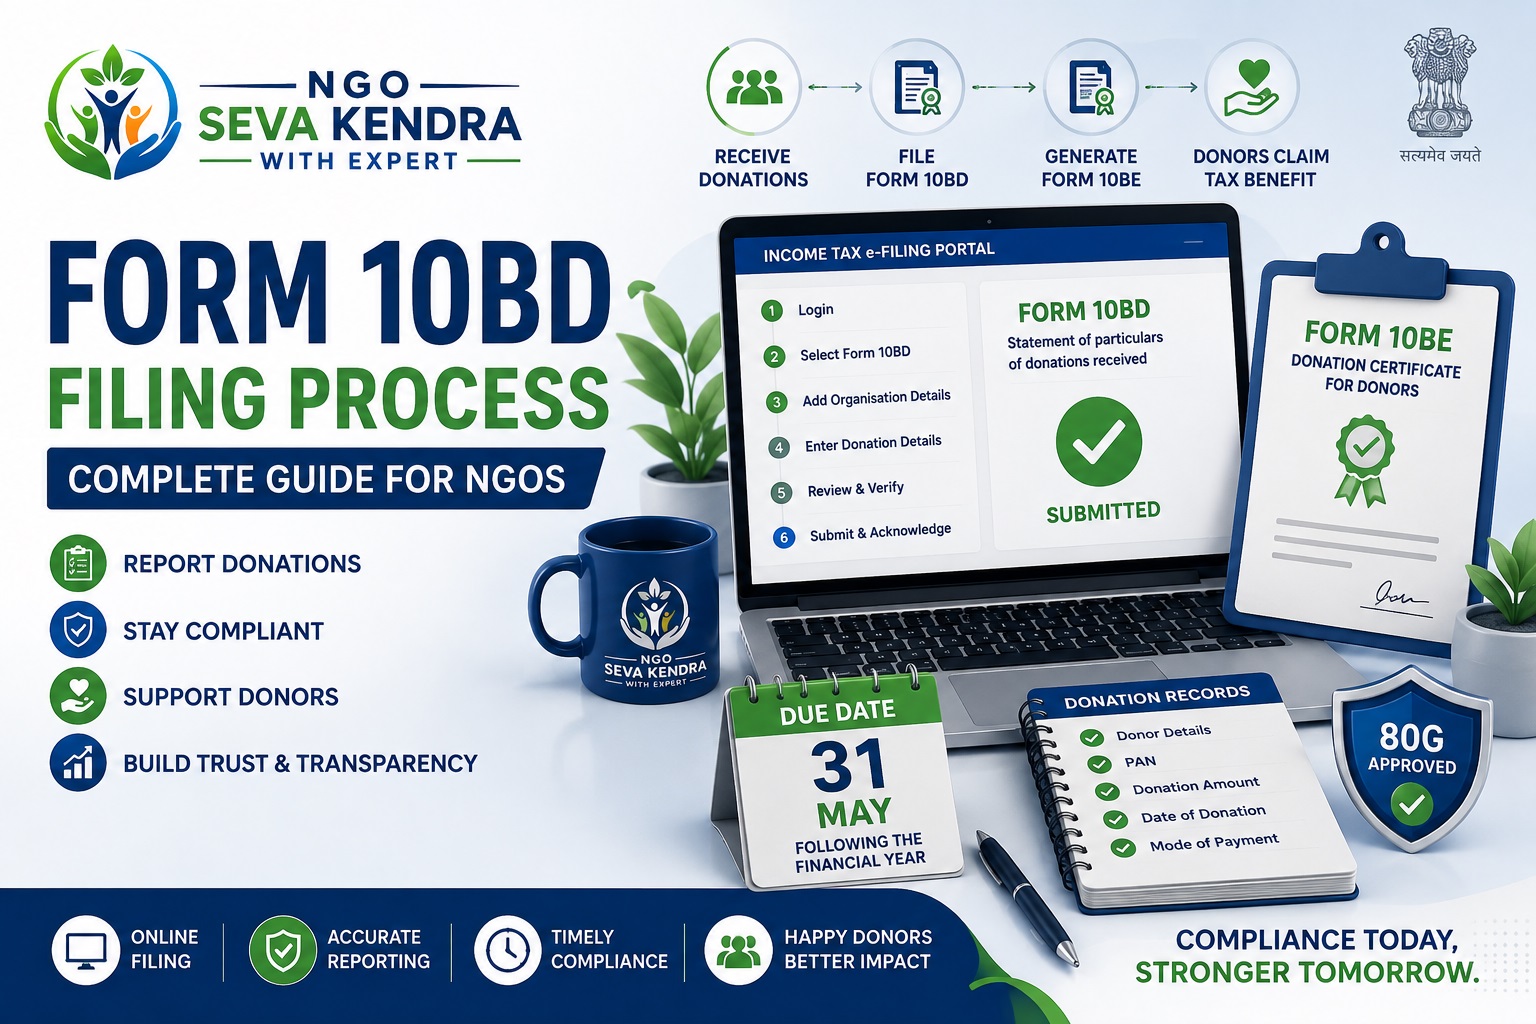
The Form 10BD filing process is completed electronically through the Income Tax e-Filing portal.
The Income Tax Department’s current user manual provides the following general workflow.
Step 1 — Log in to the Income Tax e-Filing Portal
The authorised person should log in to the organisation’s Income Tax e-Filing account using the applicable credentials.
The taxpayer/entity should have an active PAN and registered e-Filing account.
Step 2 — Go to Income Tax Forms
After logging in:
e-File → Income Tax Forms → File Income Tax Forms
The Income Tax Department’s user manual identifies this route for accessing Form 10BD.
Step 3 — Select Form 10BD
Search for or select:
Form 10BD
under the applicable Income Tax Act forms.
Select the appropriate financial year and filing type.
Step 4 — Enter Basic Information
Provide the required details of the reporting organisation.
The information should be checked carefully against the organisation’s official records before proceeding.
Step 5 — Enter Donor and Donation Details
This is one of the most important parts of the filing process.
The organisation needs to provide the required particulars relating to donors and donations received during the financial year.
Before uploading or submitting the information, reconcile the entries with the NGO’s donation records.
Important:
Do not simply copy information from old filings without checking it.
Donor names, PAN details, addresses, donation amounts and other relevant information should be reviewed for accuracy.
Step 6 — Upload the Required Data
Depending on the applicable filing workflow, donor and donation information may be entered or uploaded using the prescribed format/template available through the Income Tax portal.
The Income Tax Department’s user manual provides instructions for downloading the template, preparing the data and uploading the required file.
Step 7 — Review the Information
Before submitting the form, carefully verify:
- Organisation details
- Donor details
- PAN information
- Donation amounts
- Donation dates
- Number of donations
- Applicable categories
- Previously issued certificates, where relevant
This is an important quality-control step.
Step 8 — Complete Verification
After the relevant sections are completed, the organisation proceeds to verification.
The Income Tax Department states that Form 10BD is submitted after completing e-verification using the applicable method such as DSC or EVC/OTP, depending on the available option.
Step 9 — Submit Form 10BD
After verification, submit the form.
A successful submission/acknowledgement should be retained for the organisation’s compliance records.
Step 10 — Generate and Issue Form 10BE
After Form 10BD is filed, the organisation needs to download/generate the applicable Form 10BE certificates and provide them to the donors.
The Income Tax Department’s user manual notes that system-generated Form 10BE certificates can become available after processing of the Form 10BD filing.
What is Form 10BE?
Form 10BE is the certificate of donation provided to the donor by the eligible organisation.
It contains relevant information about the organisation and the donation, including details such as the organisation’s PAN, name, applicable approval information and donation particulars.
Why is Form 10BE important?
Form 10BE provides the donor with the required donation certificate for the applicable Section 80G deduction process.
Therefore:
NGO → Reports donation in Form 10BD → Form 10BE generated/issued → Donor receives certificate
This is an important relationship to explain to NGO clients.
Difference Between Form 10BD and Form 10BE
| Particular | Form 10BD | Form 10BE |
|---|---|---|
| Purpose | Statement of donations | Donation certificate |
| Prepared by | Eligible organisation | Issued by organisation |
| Main recipient | Income Tax Department | Donor |
| Contains | Donor and donation particulars | Certificate/details of donation |
| Purpose in compliance | Donation reporting | Evidence/certificate for donor |
| Timing | Filed annually | Issued to donors after reporting |
| Due date | 31 May following relevant financial year | 31 May following relevant financial year |
The Income Tax Department confirms that the last date for both the Form 10BD statement and Form 10BE certificate is generally 31 May immediately following the financial year in which the donation was received.
Form 10BD Due Date
The due date for filing Form 10BD is:
31 May immediately following the end of the financial year in which the donation was received.
For example:
| Financial Year | Form 10BD Due Date |
|---|---|
| FY 2025–26 | 31 May 2026 |
| FY 2026–27 | 31 May 2027 |
| FY 2027–28 | 31 May 2028 |
The Income Tax Department’s current guidance confirms this annual deadline.
Important: Always verify the applicable deadline on the Income Tax Department portal before filing, especially if any statutory extension or change has been announced.
Government Fees and Late Filing Consequences
Timely filing is important because delay can result in additional financial consequences.
According to the Income Tax Department’s current Form 10BD FAQ, delay in furnishing Form 10BD attracts a fee of ₹200 per day of delay under Section 234G. The department also states that failure to furnish the statement can attract a penalty under Section 271K, which may range from ₹10,000 to ₹1,00,000, subject to the applicable provisions.
Why NGOs should not wait until the last date
Instead of collecting all donation records at the end of the financial year, NGOs should maintain a properly organised donor database throughout the year.
This reduces:
- Data-entry errors
- PAN-related issues
- Duplicate entries
- Incorrect donation amounts
- Missing donor information
- Last-minute filing pressure
Common Mistakes While Filing Form 10BD
1. Incorrect donor information
Incorrect names, PAN details or addresses can create reporting problems.
2. Mismatch in donation amounts
The donation amount reported in Form 10BD should be reconciled with the NGO’s internal records.
3. Missing donations
Every applicable donation should be reviewed before final submission.
4. Filing after the due date
Waiting until the last day increases the risk of missing the deadline.
5. Not reconciling bank records
Donation records should ideally be reconciled with bank statements and other accounting records.
6. Incorrect Form 10BE details
Since Form 10BE is issued to donors, errors in donor information can affect the quality of the certificate.
7. Not retaining filing records
NGOs should maintain copies of the filed statement, acknowledgement, relevant donor records and issued certificates.
Benefits of Proper Form 10BD Compliance
Proper Form 10BD compliance can help an NGO:
Maintain better statutory records
Regular reporting creates a structured record of donations received.
Improve donor confidence
Accurate donation reporting and timely issuance of certificates demonstrate professional compliance practices.
Reduce avoidable penalties
Filing within the prescribed deadline helps avoid the financial consequences associated with delayed or non-filing.
Simplify annual NGO compliance
A properly maintained donor database makes future compliance work easier.
Frequently Asked Questions
What is Form 10BD?
Form 10BD is a statement of particulars of donations received that eligible trusts, institutions and NGOs covered by the applicable provisions are required to furnish to the Income Tax Department.
Who needs to file Form 10BD?
Generally, trusts, institutions and NGOs approved under Section 80G that receive applicable donations are required to file Form 10BD. Specified entities covered under Section 35(1A) may also have this reporting requirement.
What is the due date for Form 10BD?
The due date is 31 May immediately following the financial year in which the donation was received.
What happens if an NGO does not receive any donation during the financial year?
The Income Tax Department states that Form 10BD is not required if no donation was received during the financial year.
What is Form 10BE?
Form 10BE is the certificate of donation that is issued to donors after the applicable donation information has been reported through Form 10BD.
Is Form 10BD filed online?
Yes. Form 10BD is furnished electronically through the Income Tax e-Filing portal.
Is e-verification required for Form 10BD?
Yes. The Income Tax Department states that submission is completed after e-verification using the applicable verification method such as DSC or EVC/OTP.
What is the late filing fee for Form 10BD?
The Income Tax Department currently states that a fee of ₹200 per day of delay applies under Section 234G. Additional penalty provisions may also apply for failure to furnish the statement.
Can Form 10BD be revised?
Yes. The Income Tax Department’s user manual provides a process for filing a revised Form 10BD where corrections are required.
When is Form 10BE available after filing Form 10BD?
The Income Tax Department’s user manual states that system-generated Form 10BE can become available after 24 hours from filing Form 10BD.
Related NGO Services
This section should link naturally to your existing service pages.
Section 8 Company Registration
For organisations planning to establish a non-profit company under Section 8 of the Companies Act.
12A Registration
For eligible charitable organisations seeking income-tax exemption under the applicable provisions.
80G Registration
For eligible NGOs and charitable institutions seeking approval that enables donors to claim applicable deductions.
NGO Annual Compliance
For organisations that need assistance with maintaining their ongoing statutory and tax compliance.
CSR-1 Registration
For eligible implementing agencies seeking registration for undertaking CSR activities.